 Analysis by Appwee
I've got to admit, I've always been a bit skeptical about mobile banking apps. But after diving into the Current app, I might just be a convert. Let me walk you through my experience with it and why it might be worth your time.
The First Impressions
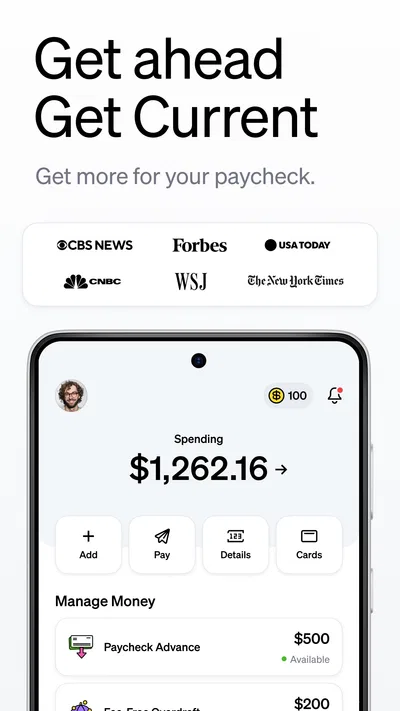
Jumping into Current, the first thing I noticed was how clean and intuitive the interface was. It’s got that modern look and feel, with everything laid out in a way that just makes sense. No more fumbling around trying to find where to transfer money or check your balance. It’s all right there, front and center.
Signing up was a breeze too. All you need is your basic info, and you’re in. I was particularly impressed by how quickly the verification process went. It didn't keep me waiting, which is always a bonus in my book.
Features That Stand Out
One of the standout features for me is the ability to get paid up to two days early with direct deposit. I mean, who wouldn’t want their paycheck a little sooner? It’s a game-changer if you’re living paycheck to paycheck. Plus, there’s no fee for overdrafts up to $100, which is a nice safety net.
Another cool feature is the Savings Pods. You can set up different pods for different goals, like saving for a vacation or a new gadget. It’s like having little piggy banks within your account, and it makes saving a bit more fun and visual.
Current also supports instant spending notifications. Every time you make a purchase, you get a ping on your phone. It helps keep track of where your money’s going and puts you in control.
Security and Peace of Mind
Now, when it comes to mobile banking, security is a biggie. With Current, they’ve got you covered. There’s 256-bit encryption, which is geek-speak for really tough security. Plus, there’s two-factor authentication for that extra layer of protection. I felt safe knowing that my financial info was in good hands.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
If you ever lose your card, you can lock it right from the app. That’s a relief, especially if you’re the type who misplaces things often.
Customer Support
We all know that sometimes things go wrong, and when they do, good customer service is a must. I had a little hiccup with a transaction and decided to test out their support. I’m happy to report that they were quick to respond and super helpful. It’s nice knowing there are real people ready to help out when needed.
Final Thoughts
So, would I recommend Current? Absolutely. It’s a solid choice for anyone looking to make their banking life easier and more efficient. The app does a fantastic job of blending functionality with ease of use, and the features are genuinely helpful.
If you’re tired of the traditional banking experience and want something that feels more 21st century, give Current a try. It might just change the way you think about your finances.
How It Fits Into a Busy Day
The app’s appeal is easiest to understand when I think about a normal payday rather than a list of features. Imagine your pay arriving while you’re commuting, then a grocery run and a few small purchases later. Early direct deposit can make the timing feel less rigid, while notifications give you a near-immediate prompt to check whether each charge matches what you just bought. That combination is useful because it connects incoming money with everyday spending instead of making banking a task you remember to do once a week.
I would use the Savings Pods for money that has a clear purpose, not as a substitute for a complete budget. Separating a weekend trip from a replacement phone fund makes the goals easier to see, and moving money toward one of them can feel more deliberate than leaving every dollar in one undifferentiated balance. The trade-off is that a pod only helps if I keep its purpose and target realistic; dividing savings into too many tiny goals can turn a simple plan into bookkeeping.
Where the Speed Matters—and Where It Doesn’t
For routine checks, a banking app should make the important task easy to reach, and the uncluttered layout I noticed supports that expectation. I value being able to look at a balance or find a transfer without wandering through unrelated screens. That is a practical kind of speed: fewer steps and less hesitation, rather than a claim that every action or transaction completes instantly.
Direct deposit arriving early can help with planning, but I would not build a bill schedule around money arriving before its expected date. I’d still use the normal payday as the dependable planning point and treat an earlier arrival as breathing room. That small habit matters most for anyone whose rent, subscriptions, or other regular obligations leave little room for timing surprises.
Notifications also change how quickly I notice a possible mistake. If a purchase alert appears while the receipt is still in my hand, it is easier to compare the amount and recognize an unfamiliar charge than it is days later. I’d keep alerts enabled if I rely on them for that purpose, while remembering that a phone notification is a prompt to review activity, not a replacement for checking the account carefully.
Handling Busy Spending Periods
The app is particularly suited to stretches when money moves in several directions: a paycheck comes in, routine bills go out, and daily card purchases accumulate. Instead of waiting until the end of the week to reconstruct what happened, I can use transaction alerts as small checkpoints. A quick glance after a busy day can help me spot a purchase I forgot about or notice that a planned expense is larger than expected.
That workflow is helpful, but it has a limit. Alerts can become background noise if every small purchase interrupts work or family time. I would treat them as a record-keeping aid and review the account at a time that suits me, rather than feeling obliged to react to every ping. People who prefer a quiet phone or already track spending in another system may find the extra stream of notifications less valuable.
There is also a useful distinction between a spending cushion and savings. The overdraft feature described here may soften a limited shortfall, but I would not treat it as a standing extension of my budget. A safer routine is to keep planned expenses visible, use a pod for money with a defined goal, and regard any overdraft protection as a fallback rather than permission to spend more.
Reliability and Getting Back on Track
My impression of reliability comes less from expecting an app to be flawless and more from having practical ways to respond when something feels wrong. Being able to lock a lost card in the app is reassuring because it gives me an immediate action to take while I work out where the card went. I would still check recent transactions afterward, since locking the card addresses future use rather than explaining activity that already took place.
If a transaction looks unfamiliar, I would first compare it with recent receipts and purchases made by anyone else who uses the account, then contact support if it still does not make sense. That order can prevent a routine merchant name or delayed recognition from becoming unnecessary worry, while leaving a clear path for genuine problems. The reported helpful support experience is encouraging, though anyone choosing a financial service should judge it by their own needs and not assume that every case will be resolved in the same way.
For account recovery, I’d keep access details current and make sure I can reach the email or phone number associated with the account. That is sensible preparation for any mobile banking app, especially when the phone itself is lost or replaced. The card-lock option is useful, but it does not remove the need to regain account access securely and review activity after changing devices.
Who Benefits Most from This Approach
I see Current as a strong fit for someone who wants everyday banking to feel visible and manageable on a phone: people who value quick balance checks, benefit from earlier direct deposits, or like dividing savings into named goals. It can also suit someone trying to pay closer attention to frequent small purchases, because the alerts make those transactions harder to overlook.
It is less compelling for a person who wants a single app to handle every part of a detailed financial plan. Savings Pods can organize a few concrete goals, but they are not the same thing as a full budgeting method with every category, long-term projection, and household obligation mapped out. If I needed extensive reporting or preferred to see several financial accounts together, I would compare Current with a traditional bank app or a dedicated budgeting tool before making it my main system.
It may also be the wrong choice for someone who is uncomfortable managing core banking tasks from a phone, has unreliable access to one, or strongly prefers speaking with a local branch representative. The mobile-first convenience is the point, but it also means that a person who wants in-person help as their normal way of banking should look for an option built around that preference.
Compared with Traditional Banking Apps
Compared with the usual bank app, Current’s strongest difference in my experience is the emphasis on day-to-day visibility: a straightforward interface, purchase notifications, goal-based savings, and the appeal of getting direct deposit early. A large traditional bank may be a better match for someone who already relies on its wider set of services or wants to manage all existing accounts in one place. I would not switch solely for a cleaner screen; the practical question is whether the app’s particular routines fit the way I receive and use money.
Compared with keeping track of spending in a spreadsheet or notes app, the advantage is that transaction alerts arrive alongside the banking activity rather than depending on me to remember every purchase. A spreadsheet can offer more control over categories and planning, but it asks for consistent manual work. Current reduces some of that friction, while still leaving me responsible for making a budget and checking that my spending fits it.
Device Expectations and Everyday Use
Current is a finance app from developer Current, and it is free to download. It is listed for everyone, with version 8.3.2 and a minimum operating-system requirement of 8.0. The app has a 4.5 average from around 176,000 ratings, with roughly 47,000 written reviews and more than five million installs. Those figures suggest that it has reached a broad audience, but they do not guarantee that it will feel equally smooth on every device.
I would expect a current, compatible phone to be the more comfortable way to use a service where timely account access matters. On an older or constrained device, I’d leave room for ordinary app delays and avoid making a last-minute transfer the only plan for an urgent payment. I can’t infer battery use, storage demands, or a precise loading time from the interface alone, so I would judge those on the phone I actually plan to use rather than assume the same performance everywhere.
For anyone deciding whether to install it, the practical test is straightforward: check that the phone meets the operating-system requirement, set up access when you have time to complete verification, and try the main routine—checking activity, understanding alerts, and organizing one savings goal—before depending on it for time-sensitive money decisions. That lets me see whether the layout and pace suit my habits without confusing convenience with a guarantee that every moment will be friction-free.
My Performance Verdict
What I like most is the way Current brings several useful habits into one mobile routine: notice purchases, keep savings goals distinct, and make the timing of direct deposit more flexible. The interface felt easy to navigate in my use, and the card-lock option gives me a concrete response to a common worry. The trade-offs are just as important: notifications need managing, savings goals still require discipline, and the app is not a replacement for a detailed budget or the wider support some people expect from a traditional bank.
Current has been around since May 5, 2017, and its large user base makes it a familiar option in mobile finance, but I would still choose it based on the way I bank rather than popularity alone. For someone who wants a clear phone-based view of everyday spending and simple goal separation, it is worth considering. If my priority were branch access, extensive planning tools, or keeping every financial service under an existing bank relationship, I would compare alternatives first. My recommendation is positive, with one practical caveat: use its convenience to build better routines, not as a reason to stop checking where your money goes.
Current - Mobile Banking Pros and Cons
- User-friendly interface with intuitive navigation.
- Real-time transaction alerts for better security.
- Wide range of banking features available.,24/7 customer support via chat and phone.
- Seamless integration with other financial apps.
- Occasional slow loading times during peak hours.
- Limited customization options for notifications.
- Requires strong internet connection for optimal use.
- Some features locked behind premium versions.
- Infrequent updates may delay bug fixes.
Current - Mobile Banking Frequently Asked Questions
What features does Current offer for managing finances?
Current provides a range of features designed to help users manage their finances effectively. These include instant spending notifications, budgeting tools, savings pods for setting aside money, and no-fee overdrafts up to $100 with qualifying direct deposits. Additionally, the app offers early access to paychecks, which can be extremely beneficial for budgeting and financial planning.
How secure is my money with the Current app?
Current prioritizes the security of its users’ money and personal information. The app uses cutting-edge security measures, including encryption and two-factor authentication, to protect accounts. Additionally, deposits are insured up to $250,000 through their partner banks, which are members of the Federal Deposit Insurance Corporation (FDIC).
Does Current charge any fees for its services?
Current is known for its transparent and minimal fee structure. There are no hidden fees, and users enjoy free overdraft protection up to $100 with qualifying direct deposits. However, some features, such as expedited card delivery or specific ATM withdrawals, may incur minimal fees, which are clearly outlined in the app.
Can I use Current for direct deposits, and how soon can I access my funds?
Yes, Current allows users to set up direct deposits. One of the key benefits is the ability to access your paycheck up to two days earlier than traditional banks. This feature helps users manage their cash flow more efficiently and can be especially useful for those who need early access to funds for expenses.
What is the user experience like with the Current app?
The Current app is designed with user experience in mind, offering an intuitive and easy-to-navigate interface. Users benefit from real-time notifications, seamless transaction histories, and straightforward budgeting tools. The app is frequently updated to include new features and enhancements based on user feedback, ensuring a smooth and satisfying experience.
Gallery